Every settlement comes down to one key choice: receive the proceeds as a lump sum, or convert some or all of them into guaranteed1 future income. In the current rate environment, the financial argument for the latter has grown considerably stronger.
The Relationship Between Interest Rates and Payment Size
Structured settlement annuities are supported by conservative, fixed-income investments. When prevailing yields are high, issuing carriers can secure more favorable returns at the time of purchase. Those returns are passed through to the claimant in the form of larger guaranteed payments over the term of the settlement.
This dynamic is widely recognized across the industry. Because the guaranteed income a claimant receives in exchange for a lump sum is materially greater when rates are elevated, the case for structuring at the time of settlement becomes far more compelling. Structured settlements also tend to move in line with federal interest rates, which means claimants can lock in favorable terms during a period of increased rates without exposure to market instability or loss of premium.
How Today's Rates Compare
A comparison of structured settlement rates over time illustrates the extent of the shift:
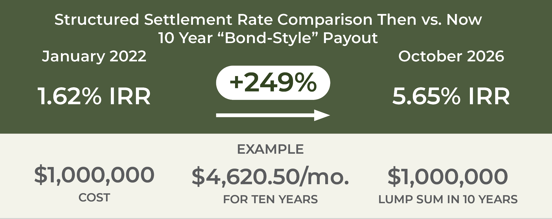
In this illustration*, a $1,000,000 purchase at current rates provides $4,620.50 per month for ten years, followed by a $1,000,000 lump sum at the end of the term. Under the rate conditions prevailing in early 2022, the same premium would have produced substantially less guaranteed income.
The Value Beyond the Yield
Rate levels are only one component of the value proposition. In contrast to traditional investment vehicles, structured settlements offer:
- Tax-free payments in cases involving personal physical injury, including the growth component
- Tax-deferred payments in non-physical injury cases and for attorney fee deferrals
- No ongoing fees or expenses
- A guaranteed rate of return
These features work in tandem. A claimant who secures a favorable rate on a physical injury settlement keeps the full value of that growth, free of income tax, while receiving a predictable income stream insulated from market volatility.
What This Means for Your Client
Prevailing rates are significantly higher than they were only a few years ago, and that differential translates directly into larger guaranteed payments. For attorneys, claimants, and their advisors, the present environment warrants a renewed examination of how structuring may serve a pending settlement.
To discuss how current rates may affect your client's settlement, contact your Sage consultant today.
*Hypothetical illustration only. Actual payments and rates will vary.
1Guarantees are subject to the claims-paying ability of the issuing insurance company.